Does landlord insurance cover water damage and boilers?


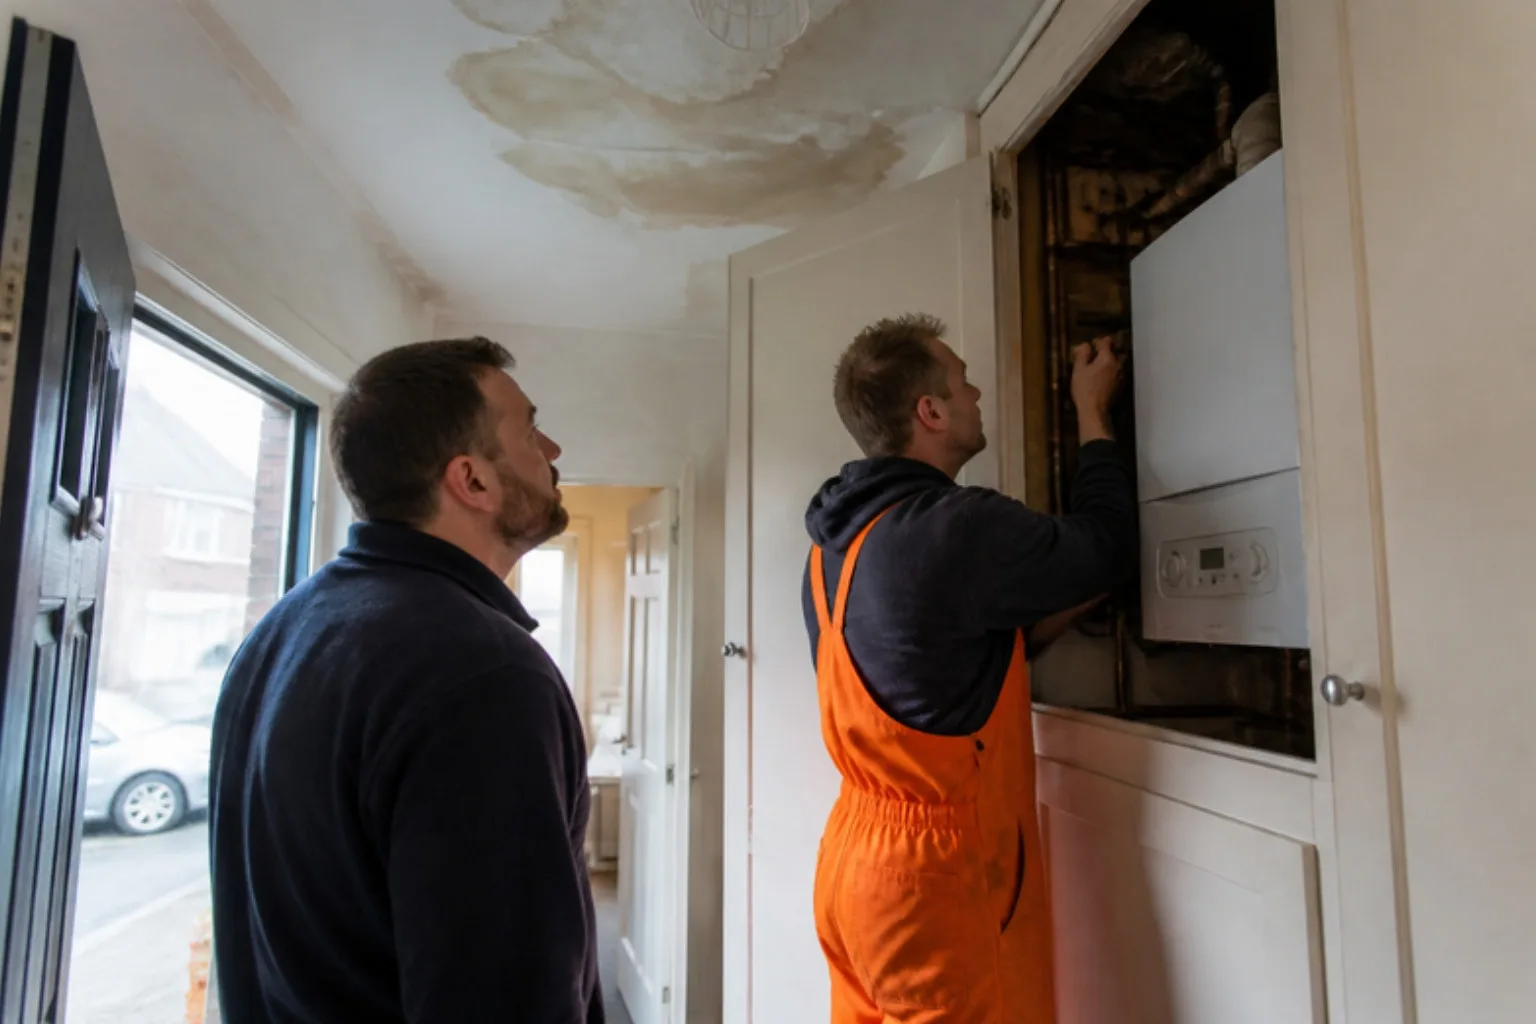
Usually yes for sudden water damage to the building, and usually no for a boiler that simply breaks down. The ABI lists burst pipes and water damage among the risks home-style policies cover, but says mechanical breakdown and wear and tear are not normally covered (ABI).
So a landlord policy may pay to repair a ceiling after a pipe bursts, but fixing the boiler is your job, or a home emergency policy’s.
What kind of water damage does a landlord policy pay for?
Most policies pay for damage from a sudden leak in the water or heating system, which insurers call “escape of water”. Think of a pipe splitting in a cold snap or a washing machine hose bursting.
Which part of the policy pays depends on what got wet:
- Buildings cover pays for the structure and fixed items, such as ceilings, plaster, floorboards and a fitted kitchen.
- Landlord contents cover pays for things you supply, such as furniture and free-standing appliances. The Financial Ombudsman treats carpets as contents, even when fitted (Financial Ombudsman).
- Loss of rent, where included, may pay rent while the property is unfit to live in after an insured leak.
For what a standard policy includes and what you can add, see the landlord insurance page on Tiger.co.uk.
When is a leak in a rental not covered?
Mainly when the leak was slow, the property was empty too long, or the damage came from poor upkeep. The Financial Ombudsman says policy exclusions often include damage that happened gradually, and some insurers exclude rot as well (Financial Ombudsman).
| What happened | Usually covered? | Why |
|---|---|---|
| A pipe bursts and floods the kitchen | Yes, under escape of water | A sudden insured event |
| A shower seal has dripped behind tiles for months | Often not | Gradual damage is a common exclusion |
| A roof leaks because tiles were never replaced | Usually not | The ABI lists lack of maintenance as an exclusion |
| A pipe bursts after the house has been empty for 10 weeks | Often not | Empty-property limits are usually 30 or 60 days |
| The leak soaks the tenant’s sofa and laptop | Not on your policy | Tenants insure their own belongings |
| The boiler stops working but nothing leaks | No | Breakdown is not an insured event |
On empty properties, the Financial Ombudsman says most policies drop cover for escape of water, theft and malicious damage after a set period, usually 30 or 60 days (Financial Ombudsman). For longer gaps between tenants, look at unoccupied property insurance.
Damp is a related grey area. Our guide on whether buildings insurance covers damp explains how insurers separate a sudden leak from slow moisture.
Does landlord insurance cover boiler breakdown or replacement?
No, not as standard. A boiler that fails through age or a worn part is a mechanical breakdown, which the ABI says home insurance does not usually cover. The ABI also points out that insurance is not a maintenance contract.
What a landlord policy may cover is the damage a boiler causes. If a boiler leaks and ruins a ceiling, the ceiling can fall under escape of water. The boiler repair usually does not.
Who has to fix a broken boiler in a let property?
You do, as the landlord. GOV.UK says landlords are always responsible for repairs to heating and hot water, gas appliances, pipes and flues (GOV.UK). In England, section 11 of the Landlord and Tenant Act 1985 requires you to keep the installations for space heating and heating water in repair and proper working order (legislation.gov.uk).
If the boiler runs on gas, HSE says you must have a gas safety check every 12 months by a Gas Safe registered engineer. You keep the record for 2 years and give tenants a copy within 28 days of the check (HSE).
Can you insure the boiler separately?
Yes, through home emergency or boiler cover, often sold as a landlord add-on. The Financial Ombudsman says these policies normally pay for a tradesperson, call-out charges and the repairs and parts needed (Financial Ombudsman).
It does not usually pay for the damage the emergency causes, so it sits alongside landlord cover. See home emergency cover on Tiger.co.uk; boiler age and claim limits vary.
Are the appliances you supply covered?
They can be covered against insured events such as fire, flood or a leak, but not for simply breaking down. The ABI gives a fridge failing at the end of its useful life as an example of breakdown that is not normally covered.
Where the cover sits depends on how the appliance is fitted. The Financial Ombudsman usually treats built-in appliances as buildings and free-standing ones as contents. So a free-standing washing machine needs landlord contents cover.
Whatever the insurance says, GOV.UK says the gas and electrical equipment you provide must be safely installed and maintained (GOV.UK).
What if your tenant causes the leak?
The tenant may have to pay. GOV.UK tells tenants that if water leaks into another flat, for example from an overflowing bath, they pay for the repairs. They also pay for damage caused by their family and friends (GOV.UK).
Cover for accidental and malicious damage by tenants varies a lot between policies, so check those sections. A tenant’s own tenants contents insurance may help with their liability.
Worked example: a burst pipe between tenancies
Callum owns a two-bed terraced house in Leeds. His tenants leave in early January, and the house sits empty while he redecorates. Three weeks later a pipe in the loft freezes and splits, bringing down the landing ceiling and soaking the stair carpet.
Because the leak was sudden and the house had been empty for less than his policy’s limit, the buildings section deals with the ceiling and plaster. The carpet is his, so his landlord contents cover handles it. Had the house been empty past the limit, the claim could have been refused.
Worked example: a boiler that fails in February
Aisha lets a flat in Manchester. Her tenant reports no heating or hot water, and the engineer says the boiler’s heat exchanger has failed. Nothing has leaked.
Her landlord policy pays nothing, as this is breakdown. Under section 11 she still has to get the heating working. A home emergency policy with boiler cover could have paid the call-out and parts, up to its limit.
Checklist: keeping water and boiler claims on track
- Book the yearly gas safety check and keep each record for 2 years
- Fix drips, failed seals and stained ceilings quickly, before they count as gradual damage
- Check how many days the property can stand empty, and tell your insurer before a long gap
- Ask whether the policy has conditions for empty spells in winter, such as heating on or water drained down
- Show tenants the stopcock and ask them to report leaks at once
- Check the escape of water excess, which some policies set apart from the standard excess
- Decide whether you want home emergency cover for the boiler itself
Is a burst pipe in a rental covered?
Usually, yes. A pipe that suddenly bursts is the classic escape of water claim, so the buildings section of landlord insurance normally pays to repair the damage. Cover can be limited if the property has been empty beyond the policy limit.
Is a slow leak covered by landlord insurance?
Often not. The Financial Ombudsman says policies commonly exclude gradual damage. If a leak has been seeping for months, the insurer may say it should have been spotted and fixed, so act on early signs.
Will a landlord policy pay lost rent after a leak?
Many policies do, if an insured leak leaves the property unfit to live in. Check the loss of rent section for the time limit and the maximum it will pay.
Does landlord insurance cover boiler replacement?
Not as standard. A boiler that wears out is breakdown, which insurers do not usually cover. Landlord home emergency or boiler cover may pay for repairs up to a limit, and replacing an old boiler is normally your own cost.
Who pays if a tenant floods the flat below?
GOV.UK tells tenants they are responsible for paying for damage they cause to another flat, such as an overflowing bath. The insurer of the damaged flat may pay the claim and then try to recover the cost from whoever caused it.
Does landlord insurance cover appliances?
It can cover appliances you supply against insured events like fire or a leak, usually under landlord contents. It does not normally pay when an appliance stops working through age or wear.
Is the landlord responsible for fixing the boiler?
Yes. GOV.UK says landlords are always responsible for repairs to heating and hot water. In England, section 11 of the Landlord and Tenant Act 1985 sets the same duty in law.
Does landlord insurance cover water damage to tenant belongings?
No. Your policy covers your building and the contents you supply. Tenants insure their own furniture, clothes and electronics with a contents policy, even when the leak started in your pipework.
What to do next
Read the escape of water, unoccupancy and breakdown sections of your current policy first. If the cover falls short, Tiger.co.uk lets you compare landlord insurance quotes from UK providers with one short form.
Letting a single home? Our buy-to-let insurance page covers the basics. Letting to a relative? See the guide on renting to family. Policies vary, so check the wording or ask the insurer before you rely on a cover.
Fact-checked by Ian Wilson, Managing Director at Tiger.co.uk. 20+ years in price comparison; MEng, Queen’s University Belfast.