What is accidental damage cover on home insurance?


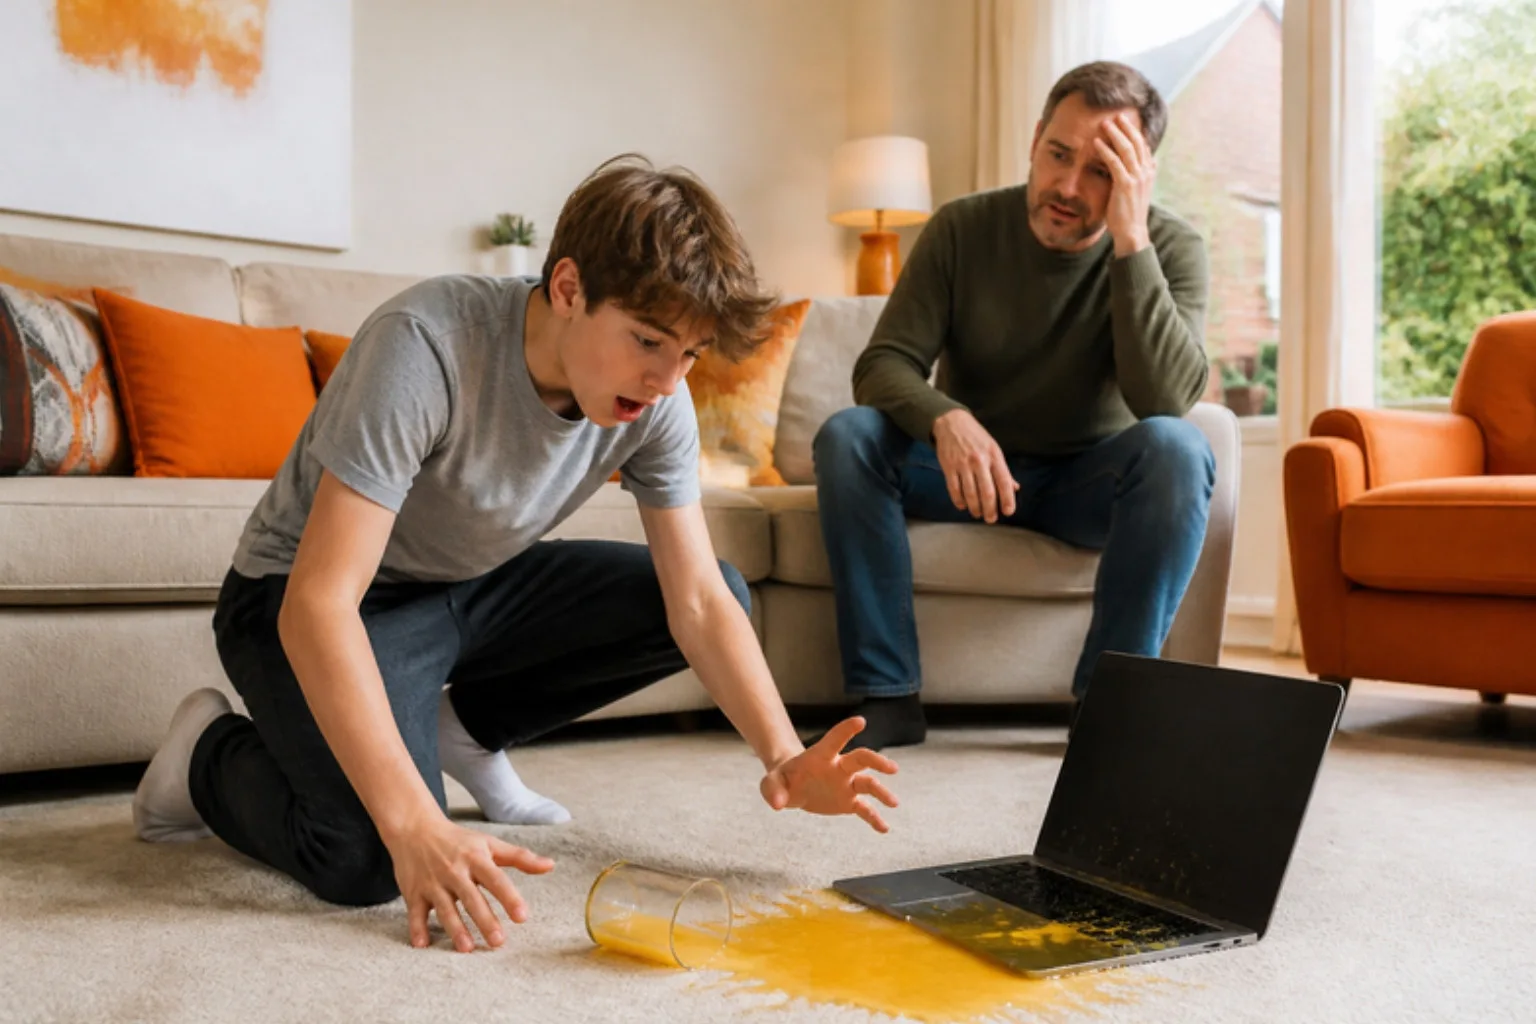
Accidental damage insurance pays to repair or replace parts of your home, or things in it, that you damage by mistake in a one-off incident. Think of a paint spill on the carpet, a nail through a hidden pipe or a TV knocked off its stand. Where a policy does not define it, the Financial Ombudsman Service treats accidental damage as something unforeseen and unintentional (FOS consumer guidance).
On many home policies it is an optional extra rather than part of the standard cover. You can usually add it to buildings, contents or both, and policies vary, so check your schedule to see what you have.
What counts as accidental damage?
Damage counts as accidental when nobody saw it coming and nobody meant it to happen. Each insurer writes its own definition into the policy wording, so the exact test can differ.
Where a policy has no definition, the ombudsman applies its own: the damage must be unforeseen and unintentional (FOS approach to accidental damage). It also says damage is not only physical breakage. A loss of function counts too, so a blocked drain can be “damaged” even with no visible crack.
Why words like “sudden” and “external” matter
Some policies say the damage must be sudden. The ombudsman notes that often means the damage itself, not the cause. Others say an external force must cause it, such as a nail hammered into a pipe behind a wall.
How does it differ on buildings and contents insurance?
It follows the part of the policy it is attached to. On buildings insurance it covers the structure and permanent fixtures, such as walls, ceilings, a fitted kitchen or a bathroom suite. On contents insurance it covers your belongings, such as furniture, electricals and rugs.
The split matters at claim time. In one ombudsman case, a homeowner had accidental cover on contents only. His glued laminate flooring was treated as part of the building, so the contents add-on did not apply (FOS case study). The ombudsman said the escape of water section was likely to cover it and told the insurer to handle the claim that way.
Which mishaps are usually covered and which are not?
The table shows how common situations tend to work. Your own policy wording decides the outcome.
| What happened | Which section would look at it | Usual position |
|---|---|---|
| You drill or nail through a pipe or cable in a wall | Buildings, with the accidental add-on | Often covered. Water damage that follows may fall under escape of water. |
| A tin of paint is knocked over onto the carpet | Contents, with the accidental add-on | Often covered if it was a genuine accident, less your excess. |
| A child knocks the TV off its stand | Contents, with the accidental add-on | Often covered. Some policies set a lower limit for TVs and laptops. |
| A bottle falls and cracks the bathroom sink | Buildings, with the add-on or limited sanitaryware cover | Often covered. |
| Your dog chews the sofa | Contents | Often excluded. Many policies leave out damage by pets. |
| A hallway carpet wears thin over the years | None | Not covered. Wear and tear is a standard exclusion. |
| A builder you paid damages the kitchen | None, usually | Usually excluded as defective workmanship. Look to the builder or their insurer. |
| You drop your phone while out shopping | Contents, only with personal possessions cover | Not covered by home accidental damage alone. |
What is usually excluded?
It does not pay for damage that builds up slowly or that someone caused on purpose. The ombudsman lists the usual exclusions as wear and tear, gradual deterioration with age, wilful or deliberate acts and defective workmanship (FOS).
Common extra exclusions include damage by pets, items that break down mechanically or electrically, and damage while the home is empty or let to tenants. Gradual problems like damp sit outside it too. Our guide on whether buildings insurance covers damp explains why.
An exclusion still has to be applied fairly. In one case, an insurer blamed wear and tear for a ring hit by a dropped pan. The ombudsman decided the impact caused the damage and told the insurer to put it right (FOS case study).
Is accidental damage cover worth paying for?
It depends on how likely an accident is in your home and whether you could pay for one yourself. Weigh up these points:
- Who lives with you: young children, teenagers and regular visitors raise the odds of spills and breakages.
- What you own: pale carpets, a large TV, glass tables or a new kitchen can be costly to put right.
- Plans for DIY or decorating: painting, drilling and moving furniture are classic causes of claims.
- Your excess: if the excess is close to the cost of a typical repair, the cover may rarely pay out.
- Your savings: if you could replace a broken TV or carpet without strain, you may prefer to keep the premium.
- Overlap with other cover: phones and laptops used outside the home may be better suited to gadget insurance.
If you rent, your landlord insures the building. Some tenants insurance policies cover accidental damage you cause to the landlord’s fixtures, which can help protect your deposit.
A worked example: one weekend of decorating
Priya and Tom own a semi-detached house in Leeds with a toddler and a spaniel. Their combined policy has the accidental add-on for both buildings and contents.
On Saturday, Tom drills into the lounge wall to hang shelves and hits a water pipe. Water soaks the plaster before he turns off the stopcock. They call the insurer that afternoon. The pipe repair and replastering are considered under the buildings section, less their excess.
On Sunday, their toddler pulls a tin of emulsion off a step and it splashes the living room carpet. That goes on the contents side, as a one-off accident.
Later that month, the spaniel chews a cushion and a chair leg. Their policy excludes pet damage, so they pay for that themselves. The cause and the wording decided each outcome.
How do you make an accidental damage claim?
Contact your insurer as soon as you can, and keep evidence of what happened. These steps help the claim go smoothly:
- Take photos straight away: show the damaged area and anything that explains how it happened.
- Hold off on repairs: many insurers want to inspect or approve costs first, except for urgent safety work.
- Keep receipts and reports: the ombudsman looks at photos, expert opinions and loss adjuster reports if a claim is disputed.
Evidence can decide a claim. In one case, an insurer refused a paint spill claim as “foreseeable” even though the policyholder had used dust sheets. Her photos showed the tin flew across the room when she tripped on the ladder, and the ombudsman found the refusal unfair (FOS case study).
Questions people ask about accidental damage
Does contents insurance cover accidental damage?
Not always. Many contents policies only include it as an optional extra, so a spill or breakage may not be covered unless you added it. Check your schedule or ask your insurer.
Is accidental damage cover worth it?
It can be if you have children, pets, valuable belongings or DIY plans, and could not easily pay for repairs. Compare the extra premium and excess with the cost of a likely accident.
Do I need accidental damage on buildings insurance?
It is not a legal requirement, but check any conditions your mortgage lender sets. It helps if you damage the structure or fixtures, such as drilling through a pipe or cracking a sink, so think about how likely that is.
Does accidental damage cover mobile phones?
Usually only inside your home. For a phone dropped while you are out, you would normally need personal possessions cover on your contents policy or separate gadget insurance.
Does accidental damage cover damage caused by pets?
Often not. Many home insurance policies exclude damage caused by pets, such as chewing, scratching or fouling, even with the accidental add-on. Check the exclusions before you rely on it.
What is the difference between limited and extended accidental damage?
Limited cover is often included as standard and only applies to named items, such as glass, sanitaryware or underground pipes. Extended cover is an add-on that applies to far more of your home or belongings.
Can I add accidental damage cover partway through my policy?
Some insurers let you add it mid-term, usually for an extra premium, so ask yours. Any new cover would only apply to accidents that happen after the change starts.
What can I do if my accidental damage claim is refused?
Complain to the insurer first. If you get no final response within 8 weeks, or you disagree with it, you can go to the Financial Ombudsman Service. You normally have 6 months from the final response.
What to do next
Check your current schedule to see whether you have accidental cover, on which sections, and at what excess. If a claim is refused and you disagree, the Financial Ombudsman Service explains how to complain and the time limits.
When you renew, look at whether each quote includes the add-on before you compare prices. Tiger.co.uk lets you compare home insurance quotes from UK insurers with one short form.
You can also read about home insurance and the difference between buildings and home insurance, or look at pet insurance. Pet insurance covers vet bills, not damage your pet causes at home. Cover and prices vary between insurers, so read the policy wording before you buy.
Fact-checked by Ian Wilson, Managing Director at Tiger.co.uk. 20+ years in price comparison; MEng, Queen’s University Belfast.